390 entry models
7 years of research and development
up to 16 years of backtested data
1 platform that has them all.
Every one of them drawn on your chart, on the bar it happened.
A new cut every day, from that day’s entry models.
The APES, the Algorithmic Precision Entry System, the charting desk it lives in, and the Mirror Desk that turns your own trading into an indicator. Same price, cancel from inside the app.
1 · The APES
Algorithmic Precision Entry System
390 entry models across - named strategies. Every one written, coded and tested before it was published, on up to 16 years of historical futures data, across ES, NQ, YM, RTY, GC, MGC, ZB and 6B.
- Every model drawn on your chart, on the bar it fired, entry, stop and target, not a arrow after the fact
- Scroll back through years of tape and watch each one fire and fail
- Its full tested record: return, CAGR, trades, win rate, drawdown, Sharpe and Calmar, published below, winners and losers
- New engines land in the book as they pass testing
2 · The charting desk
The terminal the APES runs inside. Institutional-grade charting built for reading structure, not decoration.
- Pick an engine and see its entries drawn on real bars
- 20+ indicators, multi-timeframe, full scrollback history
- Market scanner across 20 assets and 5 timeframes
- Strategy Lab and backtester, to test your own idea on the same tape
- AlgoScript, to build your own indicator without writing Python
- Connect your own broker (MT5) and trade from the chart
- Nova, the AI co-pilot, on the chart with you
3 · The Mirror Desk
Your edge, captured and turned into a tool. The APES is our research; this is yours.
- The coach watches how you actually trade
- Finds the repeatable pattern in your own results
- Forward-records it so you can see whether it really works
- Turns it into an indicator you can see, test and use
- A live coach that flags overtrading, revenge trading and oversizing while you are in it
One subscription. Cancel from inside the app.
A system that fires all day is not telling you to trade all day.
Most systems hand you an alert and leave you to it. So you sit there all session with your finger over the trigger, taking the 3am entry model with the same conviction as the 10am one, and the market at 3am is not the market at 10am. It is thinner, it is slower, and the same setup that works at the open is noise overnight.
That is not a discipline problem. It is a missing piece of information, and the strategy already knows the answer.
A Legacy Window is a half-hour slot, New York time, where a strategy has actually earned its keep. Each is scored per weekday, on net R and on accuracy, and has to clear a floor before it counts as a window at all. Tuesday at 10:00 and Thursday at 10:00 are judged separately, because they are different days.
They are calculated from what has already happened, never from the session being traded. A window is a record, not a forecast.
Here is one real system, Market Killer, over sixteen years of its own closed trades (June 2010 to June 2026). Same entries, same bracket. The only difference is when you take them.
Each bar is one whole day, midnight to midnight, New York time. The gold mark is the only half hour this system has earned. The rest of the day, it says leave it alone.

It does not send you alerts. It does something better. An alert arrives whenever it arrives, which is usually while you are at work, asleep, or halfway through something else. Most people miss them even when they set them. So the alert becomes one more thing to feel guilty about.
A window is the opposite. It is known in advance. You can put it in your calendar on Sunday night, because the answer for Tuesday does not change on Tuesday.
Read the bottom two rows, because that is the whole argument. Same system, same sixteen years, same bracket. Traded indiscriminately it takes 14,377 trades to finish at -13.55R. Traded only inside its own windows it takes 569 and finishes at +78.57R.
The other 13,808 trades were not bad luck. They were work, commission and risk that paid nothing.
Look at the red card above. That is what taking every entry looks like, over sixteen years, from a system that is genuinely good inside its windows. The entries were not the problem. The timing was.
A Legacy Window turns all of that around. You know the half hour before it arrives, on Sunday night. You are at the screen early, reading price, and you enter on your terms instead of chasing someone else's. Outside it, you are free to live your life. And you are learning when your strategy works, which is a skill you keep, instead of renting somebody else's timing every month.
And it will tell you to do nothing. Four weekdays in the table above are not the green one. A product that sells you alerts has no reason to ever say "not today", and this says it most of the week.
The honest limit: a window is computed from trades that have already closed. It is a record, not a forecast, and it says nothing about the session you are about to trade.
Seven years of trading. Then I built a way to test what I thought I knew.
I've traded for seven years. During that time I went through dozens of mentorships. Some ideas helped. Most didn't hold up for me. I kept the useful parts, questioned the rest, and spent years trying to understand which market behaviours actually repeated.
I was also building things long before I was trading. I started teaching myself to program in sixth grade on a TI-83+, worked my way through a thick C++ book, and later studied video game design. When AI became publicly available, I saw a way to connect those two sides of my life.
The work started in a chat. I brought in the setups, rules and observations I had collected over years of trading. I challenged them, translated them into code, and tested them against historical market data. That grew into an AI-assisted research lab capable of generating strategy candidates, running backtests, comparing results, and showing me where an idea broke down.
In less than seven days, that lab explored roughly a hundred times as many candidate strategies as I had discovered on my own in seven years. It did work I could never have reviewed manually at that scale without fatigue, missed details, and a lot more time.
The surprising part was how much failed. We put idea after idea against the data. Some looked brilliant on a chart and fell apart when the rules were applied consistently. Others only held up in certain markets or at certain times. Out of that process, a small handful of core mechanics kept earning a closer look.
Those mechanics became the foundation for the models you see in the APES. We wrote the rules, coded the entries and exits, tested them against years of historical data, and put the results where you can inspect them, including the losses. The charting desk draws the entry models on the bars where they occurred. You can scroll back and examine what happened for yourself.
I was like you. I thought high reward to risk was everything. Then I actually ran the numbers.
I was taught the same thing you were. Risk one to make three. A trade that risks more than it targets is a beginner's mistake. I believed it for years, and I passed on setups because the ratio didn't look the way I'd been told it should.
Then the lab let me test it instead of believe it. Thousands of strategies, the same rules applied every time, across years of data. The paradigm didn't hold. Reward to risk on its own tells you almost nothing. What matters is how often the target is reached before the stop, and those two numbers only mean something together.
That is why every strategy we test lands in one of two types.
Payoff strategies. Tight stop, far target. They lose often, and they depend on the occasional big winner to pay for the losing streaks in between. This is the one everybody is taught.
Accuracy strategies. The target sits closer than the stop. They are right most of the time, and each loss costs more than a single win pays. This is the one everybody is told to avoid.
Neither is better by default. Both can work and both can fail. Which one survives depends on the rules you are trading under, and that is the part nobody explains.
Trailing drawdown. Your loss limit follows your best balance up and never comes back down. A payoff strategy needs room to sit through a losing streak while it waits for the big winner. A trailing limit takes that room away at exactly the moment the strategy needs it.
Forced close at the end of the day. A far target that needed tomorrow's move gets closed today, at whatever price is on the screen. The big winners a payoff strategy is built on get cut short, while every stop it took along the way still cost the full amount.
News rules. The sessions where price actually travels far enough to reach a distant target are often the sessions you are not allowed to trade.
Put the three together and the textbook way to trade is the one the rules punish hardest. The game is tilted, heavily, toward the house. People fail, pay again, and blame their discipline, when nobody told them the rules change how you trade, how you manage risk, and which kind of strategy can survive at all.
You will notice most of these entry models are longs. That is not a bias. It is what the data left standing.
Think about what is actually being traded. A stock index is a basket of the largest companies in the country. Those companies grow their earnings, buy back their own shares, and are priced in a currency that loses value every single year. The index is built to drop the losers and keep the winners. Gold is priced in that same shrinking currency.
Every one of those forces pushes the same way, and they have pushed that way for decades. Shorting it means betting against all of them at once.
Try it yourself. Pull up a long-term chart of the Nasdaq, the S&P, the Dow, the Russell or gold. Zoom all the way out. Now tell me where a long-term sell would have worked.
You will find drops. Sharp ones. But they are one-offs, and every one of them was bought back and then some. A strategy that needs to catch the next one-off is a strategy that sits there losing while it waits.
What the entry models look like on a chart
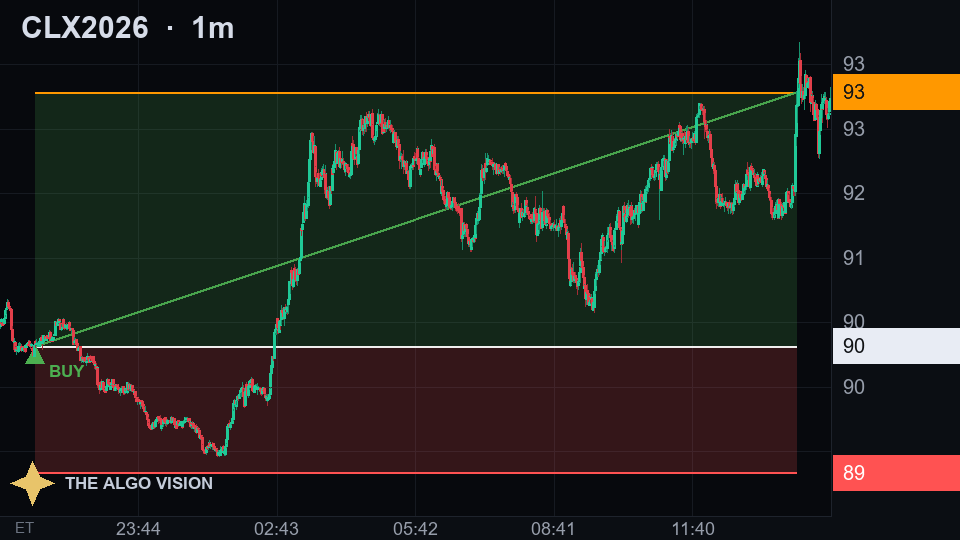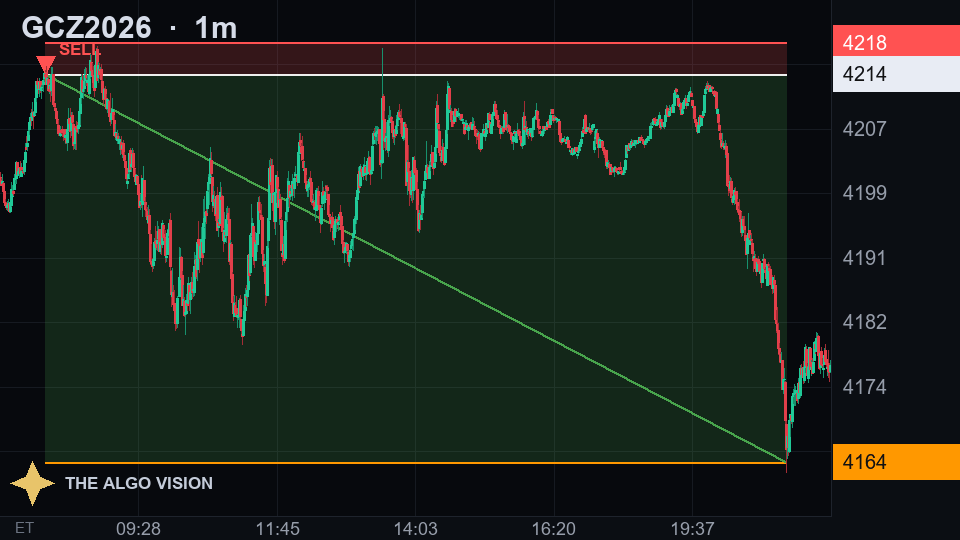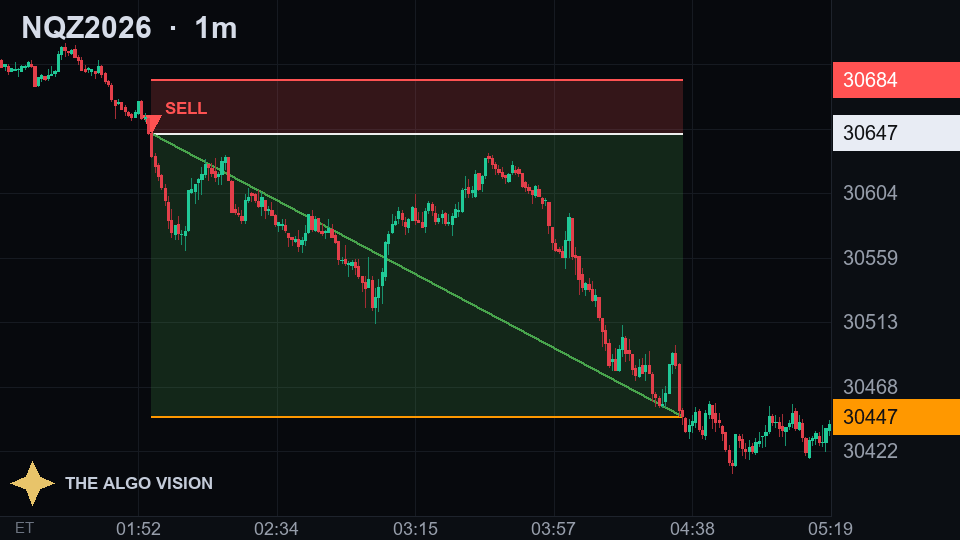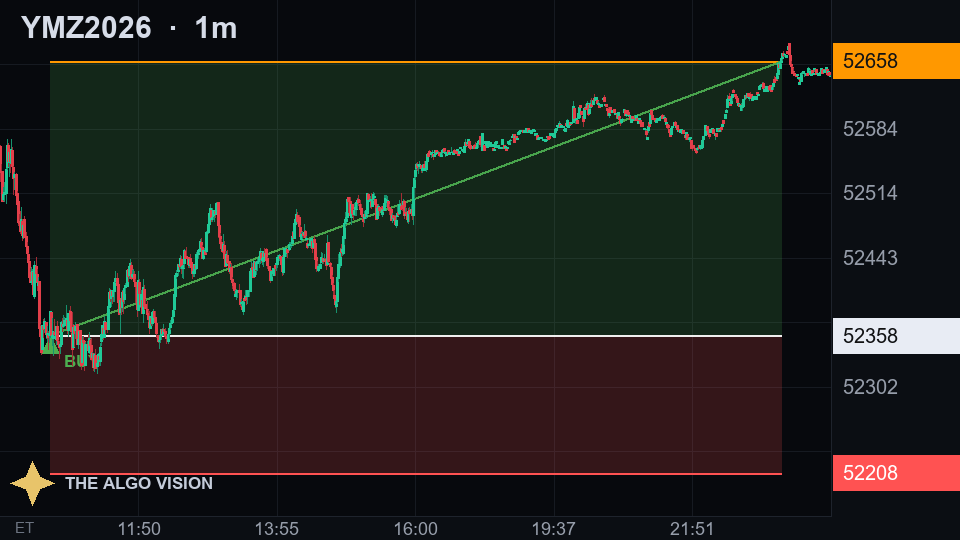
Historical snapshots of entry models from before today, drawn on the bars they fired on. Backtests, not financial gain. Past results do not predict future ones.
Every strategy, and what it actually did
Ranked by total return. The ones that finished negative are here too, the winners mean nothing without them.
- Test period varies by market and model. The longest tapes run about 16 years, gold about 15.7 and RTY about 9. Every row carries its own span, and a row that does not expose one shows a dash.
- Fills are taken at the next bar's open, never on the entry bar itself.
- A bar that covers both the stop and the target is counted as a loss. Inside one bar we cannot know which came first, and resolving the tie the other way is how a backtest invents an edge it does not have.
- The book's own risk convention is applied: a two loss daily cap and a forced close at the end of the session.
- Costs are not deducted. No commission, no slippage, no spread, no exchange or financing fees are modelled anywhere in these results. Real trading pays all of them, and on a high frequency model they matter.
- Percentage returns depend on position sizing, and the sizing behind them is not uniform. Measured across the 143 rows that carry both a percentage drawdown and a drawdown in R, the implied risk per trade runs from 0.057% to 3.99%, and varies by a median factor of 5.4 inside a single strategy. So a percentage in one row is not on the same footing as a percentage in another, and we are not going to pretend otherwise by recomputing them all onto a number the research did not use.
- Compare on R, not on percent. The reward to risk ratio, the max drawdown in R and the winning and losing runs do not depend on sizing at all. To convert R into your own account: at 0.30% risk per trade, a 40R drawdown is about a 12% account drawdown and a 100R drawdown is about 30%. That is R multiplied by your risk, which is the simple version and the more cautious one: sizing off a shrinking balance instead gives 11% and 26%. Pick your own risk and the same arithmetic works.
- In sample is data a model was built and tuned on. Out of sample is data it has never seen. A result that only holds up in sample is a story about the past. One that survives out of sample is evidence.
- One strategy in here carries a proper locked split. It was tuned on data up to April 2023, then run once on the untouched three years that followed. The untuned settings beat every tuned alternative on that unseen data. That is the standard we want on all of it.
- The same file records why it is still filed as Caution rather than Confirmed. Once you adjust for how many parameter combinations were tried before that result appeared, its Sharpe is barely better than a coin flip. That note ships with the strategy. You get the doubt as well as the number.
- Others carry weaker evidence and say so themselves. One records that its validation is consistency across eight of nine years, which is not the same thing as a holdout, and it says so in its own notes rather than in a footnote here.
- Why this matters to you. A number with no holdout behind it tells you what already happened, not what is likely to happen next. Knowing which of the two you are reading is the difference between researching a model and believing one, which is why the evidence and its limits ship with every strategy.
These are BACKTEST results, not a report of financial gain. No money was traded for any figure on this page.
Loading the record…
The things people actually ask before they join.
Does this work on TradingView?
Does it send alerts to my phone when a setup happens?
Can I use the desk for the research and place my trades somewhere else?
Do I have to connect a broker?
Which brokers can I connect?
Can I use this with a prop firm or a funded account?
Does it trade for me?
Do you tell me what to trade?
Do I need to know how to code?
Which markets were these tested on?
How much do I actually get?
What does it cost, and can I cancel?
Will this make me money?
Come and see it on your own chart.
$99 per month · cancel from inside the app
Get access, $99/moRisk disclosure and terms
Educational tools only. Everything on this page, and everything sold by The Algo Vision, is provided for education and research. It is not financial, investment, tax or legal advice, and nothing here is personalised to your circumstances, your account or your risk tolerance. We are not a broker and not a dealer. We do not hold customer funds, we do not take discretion over any account, and we do not place trades for you.
What the products actually do. The APES publishes standardized model outputs: a fixed set of rules, the same for every customer, applied to market data and drawn on a chart. They are not tailored to any individual. Where a strategy can place an order, it does so only on a customer authorized basis, from rules the customer has switched on themselves, in the customer's own brokerage account. The Mirror Desk analyses a trader's own past trading retrospectively, to describe what they already do.
The trading decision is yours. These outputs are supplied for study. Whether to act on any of them, in what size, and with what risk, is entirely your decision and your responsibility. Trading futures and other leveraged instruments involves substantial risk of loss and is not suitable for every investor.
Hypothetical results. The figures on this page are BACKTESTED, not traded. No money was placed at risk to produce any number shown. Hypothetical performance results have many inherent limitations. Unlike an actual record, simulated results do not represent actual trading and may under-compensate or over-compensate for the impact of factors such as lack of liquidity, slippage, commissions and fees. Simulated programs are generally designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profits or losses similar to those shown.
Futures and forex carry substantial risk. Trading futures, foreign exchange and other leveraged instruments carries a high level of risk and is not suitable for every investor. Leverage works against you as much as for you. You can lose some or all of your initial deposit, and in some circumstances you can lose MORE than your initial deposit and be liable for the difference. Before trading you should carefully consider your objectives, your experience and your appetite for risk, and seek independent advice if you are in any doubt. Do not trade with money you cannot afford to lose.
Past performance is not indicative of future results. A strategy that performed well over historical data may perform differently, or fail, in live markets. Market conditions change.
No liability. The Algo Vision, its owners and its staff accept no responsibility or liability whatsoever for any trading decision you make or for any outcome of it, profit or loss, arising from the use of this site, our tools, our research or any material we publish. You trade your own account at your own risk.
Most people who attempt to trade lose money. We teach practice and risk management first for that reason.